
When an investment falls, “stay calm” is easy advice to give and difficult advice to follow. Your account balance is real money, and a loss can collide with rent, a family expense or a change in employment.
A useful response begins by separating a falling price from a failing plan. Sometimes the allocation is still suitable. Sometimes the decline reveals that the original position was too large, too concentrated or funded with money needed soon.
Do you need the money, or do you need reassurance?
Check the spending calendar before the price chart. Money needed for a near-term obligation should not depend on a market recovery happening on schedule. Emergency liquidity and essential payments are separate from a long-term investment thesis.
If your circumstances have not changed, write down why you bought the holding and what would justify changing the position. “The screen is red” is different from a deterioration in a company's finances, a change in a fund's objective or discovering risks you did not understand.
Why recovery takes more than reversing the loss
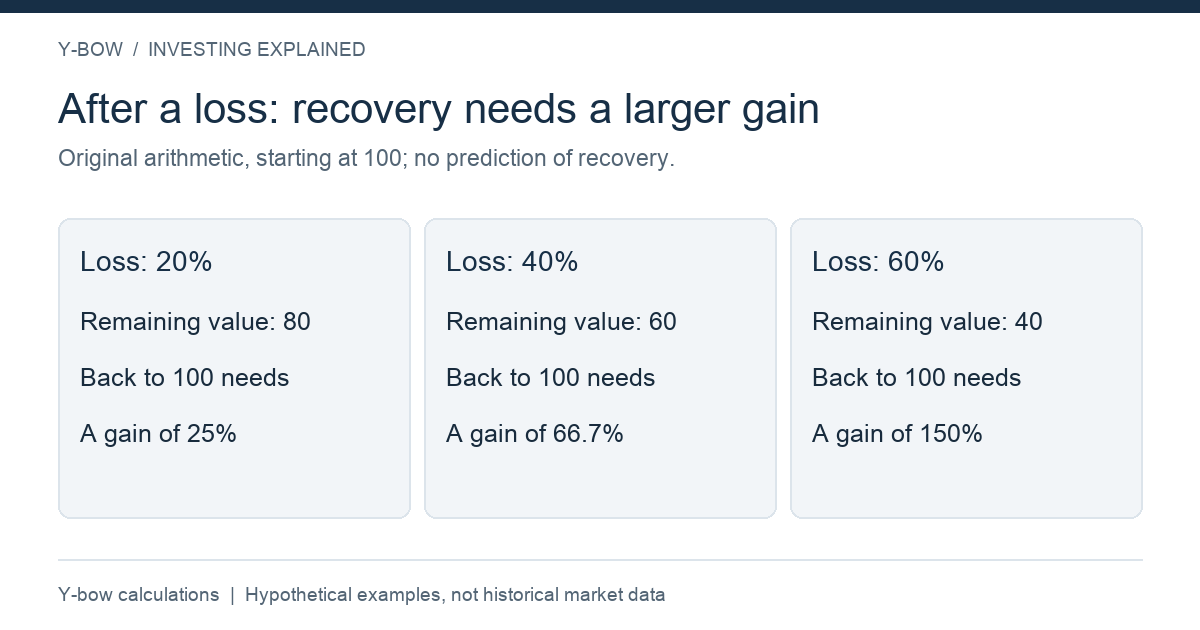
A percentage gain is calculated on the smaller remaining balance. The gain required to recover a loss is 1 ÷ (1 − loss) − 1.
| Loss from the starting value | Remaining value from 100 | Gain needed to return to 100 |
|---|---|---|
| 10% | 90 | 11.1% |
| 20% | 80 | 25% |
| 40% | 60 | 66.7% |
| 60% | 40 | 150% |
This original calculation does not predict when recovery will happen or whether an individual investment will recover at all. A diversified equity market, a single company and a leveraged fund do not share an identical recovery mechanism.
Holding, selling and rebalancing can each be reasonable
Holding may fit a funded long-term plan with an acceptable allocation. It is not justified merely by refusing to admit a mistake. A company's shares can suffer a permanent loss, and broad markets can remain disappointing for a substantial period.
Selling or reducing a position may be appropriate when money is needed, leverage is excessive or the original investment case no longer holds. The purpose is to repair the plan, not to guarantee the next market move.
Rebalancing returns the portfolio toward a chosen allocation. That may involve buying an asset after it falls, but only within a budget you can fund. Borrowing money to average down is a different decision and can create forced-sale risk.
Build a short decision checklist
| Question | Practical implication |
|---|---|
| Are essential expenses covered without selling this asset? | Check cash reserves and timing first |
| Has the holding changed, or only its price? | Read filings and the product's objective |
| Is the allocation still affordable after another fall? | Reassess size and concentration |
| Does a proposed action follow a written rule? | Distinguish a planned review from a headline response |
Daily market monitoring is not a substitute for these checks. Repeatedly opening an account can make a fluctuating number feel like a stream of new information when nothing material has changed.
I have 17 years of investing experience, but that does not let me know the date of the next recovery. Experience is more useful when it helps distinguish an uncomfortable investment from an unaffordable one.
Plan for the next difficult period
Record your target allocation, contribution budget and review schedule during a quieter period. Include what you would do if household income fell at the same time as markets. A plan based only on price volatility misses that second risk.
Our diversification article explains why spreading holdings can reduce some risks without eliminating market losses. For high-risk products, the daily leverage explanation adds the effects of compounding and costs.
This article adapts the Japanese discussion of investing during crashes. Its practical conclusion is conditional: use a reviewable plan, rather than an unconditional promise that holding any stock will eventually solve the problem.
Sources and review date
Reviewed October 14, 2026 using the SEC's asset allocation and rebalancing guidance. The loss/recovery table is an original mathematical illustration, not market data or a forecast. Investment and tax decisions depend on personal circumstances and local rules.





Comments