
A cloud company announces hundreds of billions of dollars in contracted business. It sounds as though years of growth have been secured. If you own AI infrastructure or memory stocks, the temptation is to treat that headline as reassurance for your own holdings.
Then borrowing rises, capital expenditure accelerates, or free cash flow stays negative. The numbers may be describing different stages of the same project. The question is how a contract becomes delivered service, collected cash and, eventually, a return on the capital committed.
Primary disclosures checked October 24, 2026. Company figures retain their reporting dates. All numerical diagrams are hypothetical and do not model a named company’s contracts.
What does RPO mean in cloud earnings?
Remaining performance obligations describe transaction price allocated to contractual promises that have not yet been satisfied, or satisfied only in part. “Backlog” can have a different scope when management uses it as a commercial measure. Do not assume the labels are interchangeable across companies.
Before comparing headline totals, write down what each company counts. Is the amount contracted? Does a wider commercial backlog include potential orders or options? Which products and services are included? A precise definition is more useful than an impressive-looking ranking.
Signing a contract does not make its full value current revenue
A simple cloud service may generate revenue as the service is provided. A contract containing software, hardware and services can require different allocation and recognition patterns. Dividing every contract equally by its term will not necessarily reproduce reported accounting.
The broad principle is recognition as promised goods or services transfer to the customer. The IFRS Foundation’s overview of IFRS 15 explains that framework. For the US companies discussed here, their own US GAAP policies and disclosures govern the specific treatment.
RPO vs revenue vs cash: a three-year example
Assume an imaginary single service delivered evenly over three years for a price of 120. The customer pays everything at the start; revenue is recognized at 40 per year. Money units are arbitrary. This is a deliberately simplified example without a significant financing component.
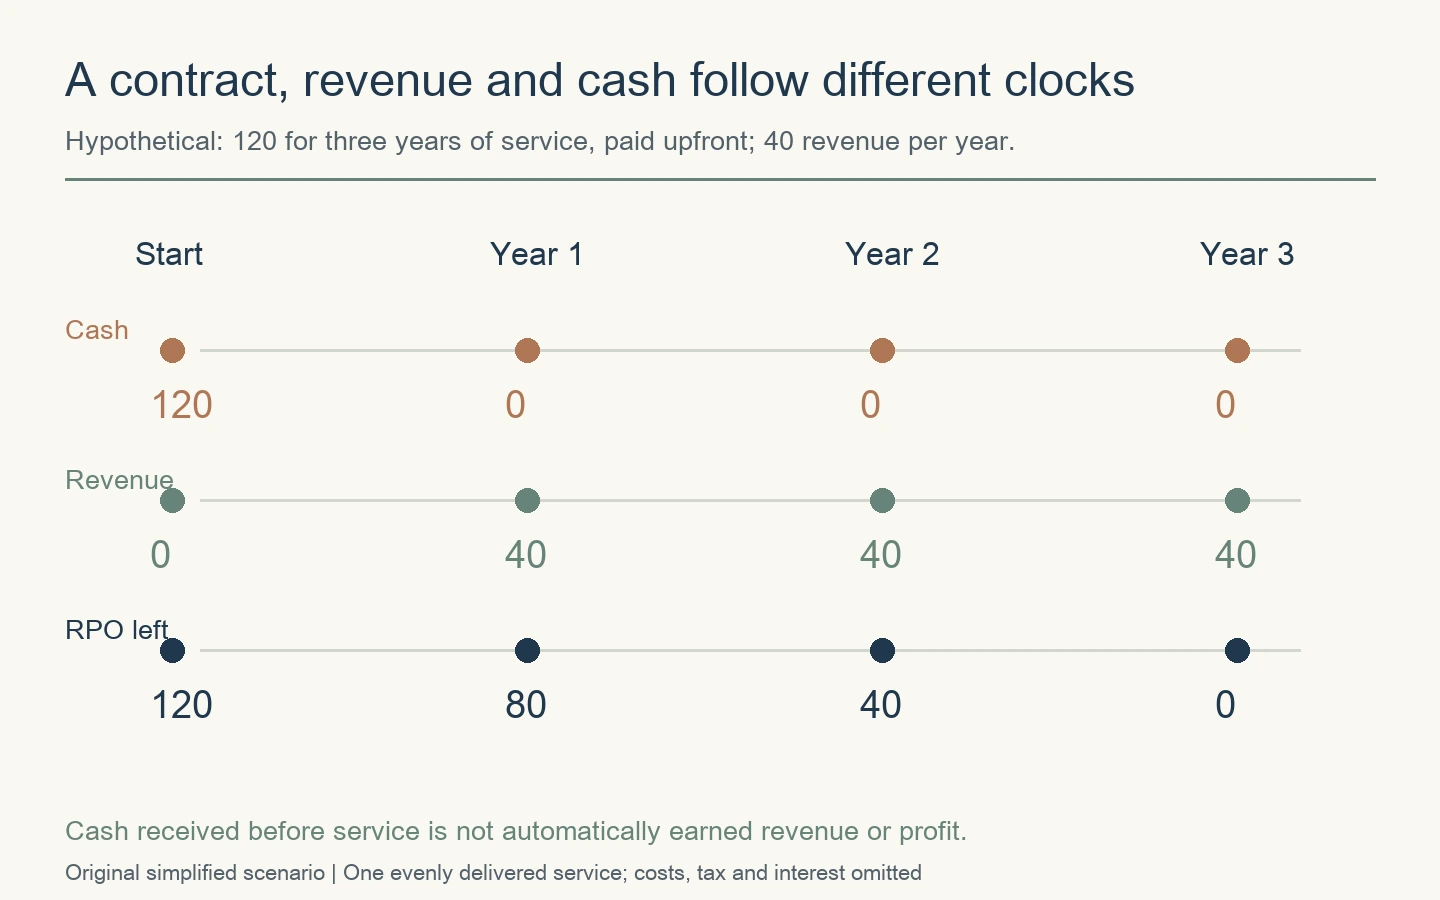
The initial cash receipt does not mean the company has earned all the revenue or profit. It still owes the service. If payment were made after delivery instead, the company could report revenue before collecting cash. The payment schedule changes funding needs without making those schedules interchangeable.
← Swipe to view the full table →
| Measure | What to examine | What it does not establish |
|---|---|---|
| RPO | The disclosed pool of unrecognized contractual revenue | Cash already collected, profit or completed facilities |
| Revenue | Amount recognized during the reporting period | That every dollar was collected in that period |
| Deferred / unearned revenue | A contract liability when billing or receipts precede delivery | Additional demand to add again to RPO |
| Operating cash flow | Cash from operating activities | Cash after all investment and financing |
| Free cash flow | The issuer-defined calculation, often operating CF less capex | Uniform definitions or guaranteed future returns |
Do not count deferred revenue twice
If a company’s RPO definition already includes billed but unearned amounts, adding deferred revenue again double-counts part of the same contract. Billing and collection are also different. A billed amount can remain unpaid, so a contract-liability balance is not a bank statement.
And receiving 120 does not remove future electricity, staffing, maintenance and replacement costs. “Cash received,” “revenue earned” and “profit available to owners” answer different questions.
Current RPO and recognition timing matter more than the total alone
Two businesses can each disclose RPO of 100. One expects to recognize 70 in the next twelve months; the other expects only 20. Their near-term revenue visibility is different even before considering margins or collection terms.
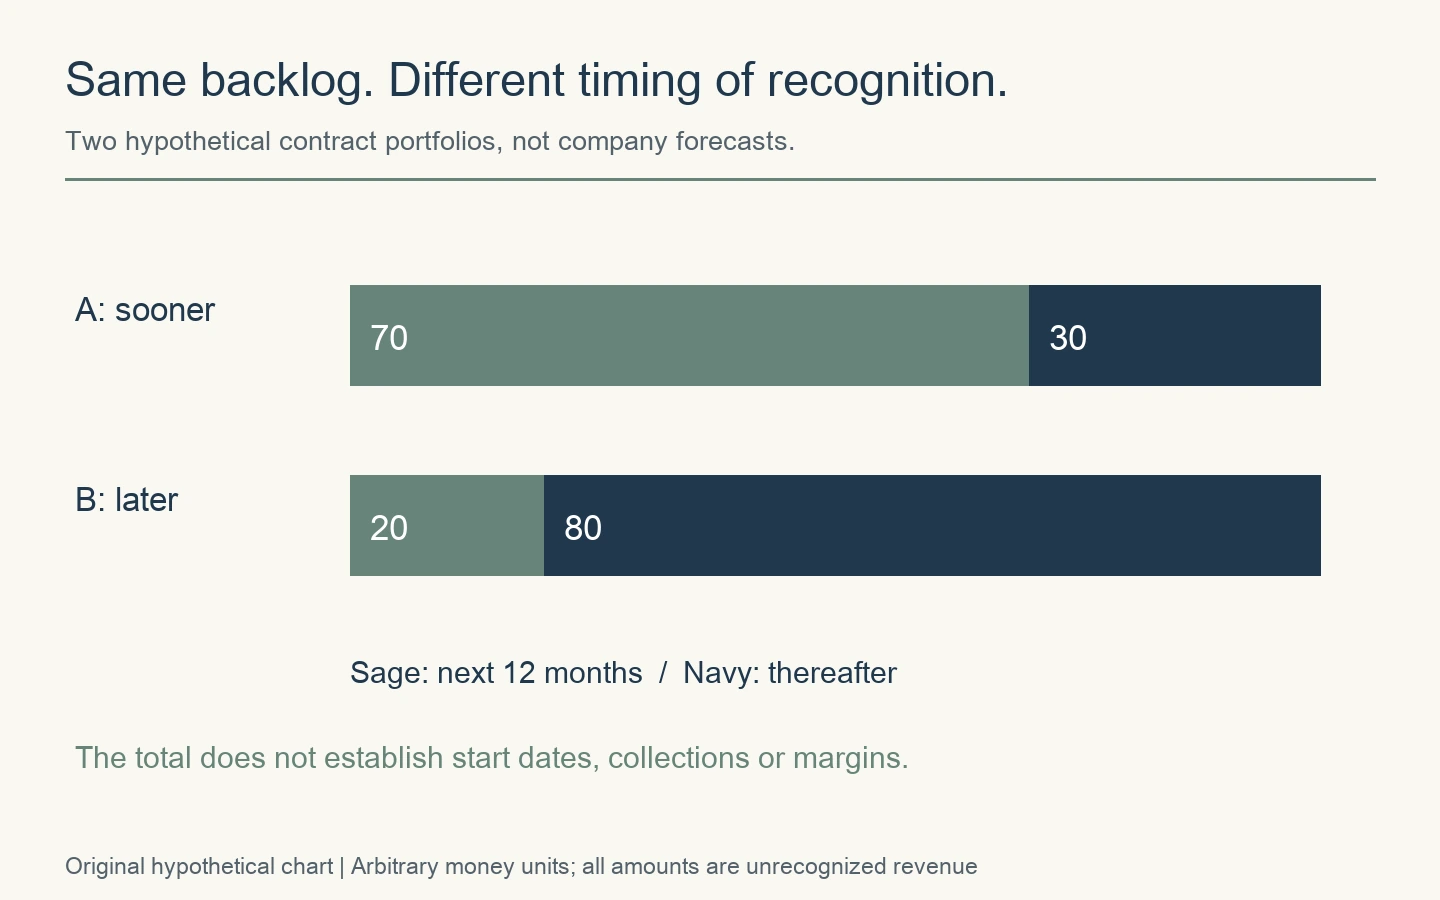
When a company uses “current RPO,” check its exact definition and period, commonly the expected recognition over the following twelve months. Do not confuse this operating disclosure with a balance-sheet current-liability classification.
Why RPO divided by annual revenue is not “years guaranteed”
In a fictional business, RPO of 100 divided by annual revenue of 50 equals two. But the numerator is a stock at a date; the denominator is a past flow over a year. The result is neither a contractual average term nor a promise that the next two years will match the previous one.
A larger ratio could reflect longer contracts or later start dates. Comparing it across different business mixes can obscure rather than clarify risk. Expected recognition, delivery milestones and collections provide the missing time dimension.
Advertisement
Microsoft and Oracle: compare disclosure boundaries before amounts
At June 30, 2026, Microsoft reported total RPO of $684 billion and commercial RPO of $678 billion, expecting to recognize approximately 30% of each over the following twelve months. These are different scopes, and neither is an AI-only figure. See annual report Note 12 and the commercial metric definition.
Oracle’s September 10, 2026 FY27 first-quarter release reported $664 billion of RPO and $19.3 billion of quarterly revenue. Its period and contract mix differ from Microsoft’s. Ranking these as comparable “AI orders” would discard the information needed to interpret them.
← Swipe to view the full table →
| Example | Date and scope | Reading discipline |
|---|---|---|
| Microsoft commercial RPO | June 30, 2026; commercial business | Not exclusively AI contracts |
| Microsoft total RPO | Same date; total company | Do not add it to the commercial subset |
| Oracle RPO | FY27 Q1 release dated September 10, 2026 | Different reporting period and contract population |
| Across both | Definitions, recognition and funding | Keep backlog, revenue, collections and profit separate |
A more recent release is not automatically a better comparison. First match the reporting date, products, contract terms and currency basis. Forecast recognition is management’s expectation, not a separate promise that execution and customer circumstances cannot change.
Customer prepayments and supplied GPUs: who funds delivery?
Oracle’s June 2026 full-year release described many large AI contracts behind recent growth as involving customer prepayments for GPUs or customer-supplied GPUs. That dated company explanation does not imply that every dollar of RPO is prepaid or that all infrastructure funding needs disappear.
Ask which party buys the accelerator, owns it, replaces it and pays for electricity, buildings and networking. A customer providing hardware changes one part of the capital requirement; it does not answer every question about the economics of service delivery.
Earlier cash can improve funding without proving attractive margins
A customer paying first can reduce the provider’s financing gap. It cannot, by itself, rescue an underpriced contract or eliminate rising operating and replacement costs. Nor does an investment-led cash outflow, by itself, prove demand is fictitious.
To judge the bridge, examine the cash needed before service begins, available funding, expected utilization and the cost of fulfilling the commitment. For the separate accounting question, see our guide to AI capex, GPU useful lives and free cash flow.
A flat RPO balance can conceal substantial new business
Imagine an opening balance of 100. New or expanded contracts add 40, recognized revenue removes 30, and an illustrative cancellation adjustment removes 10. The closing balance is still 100.
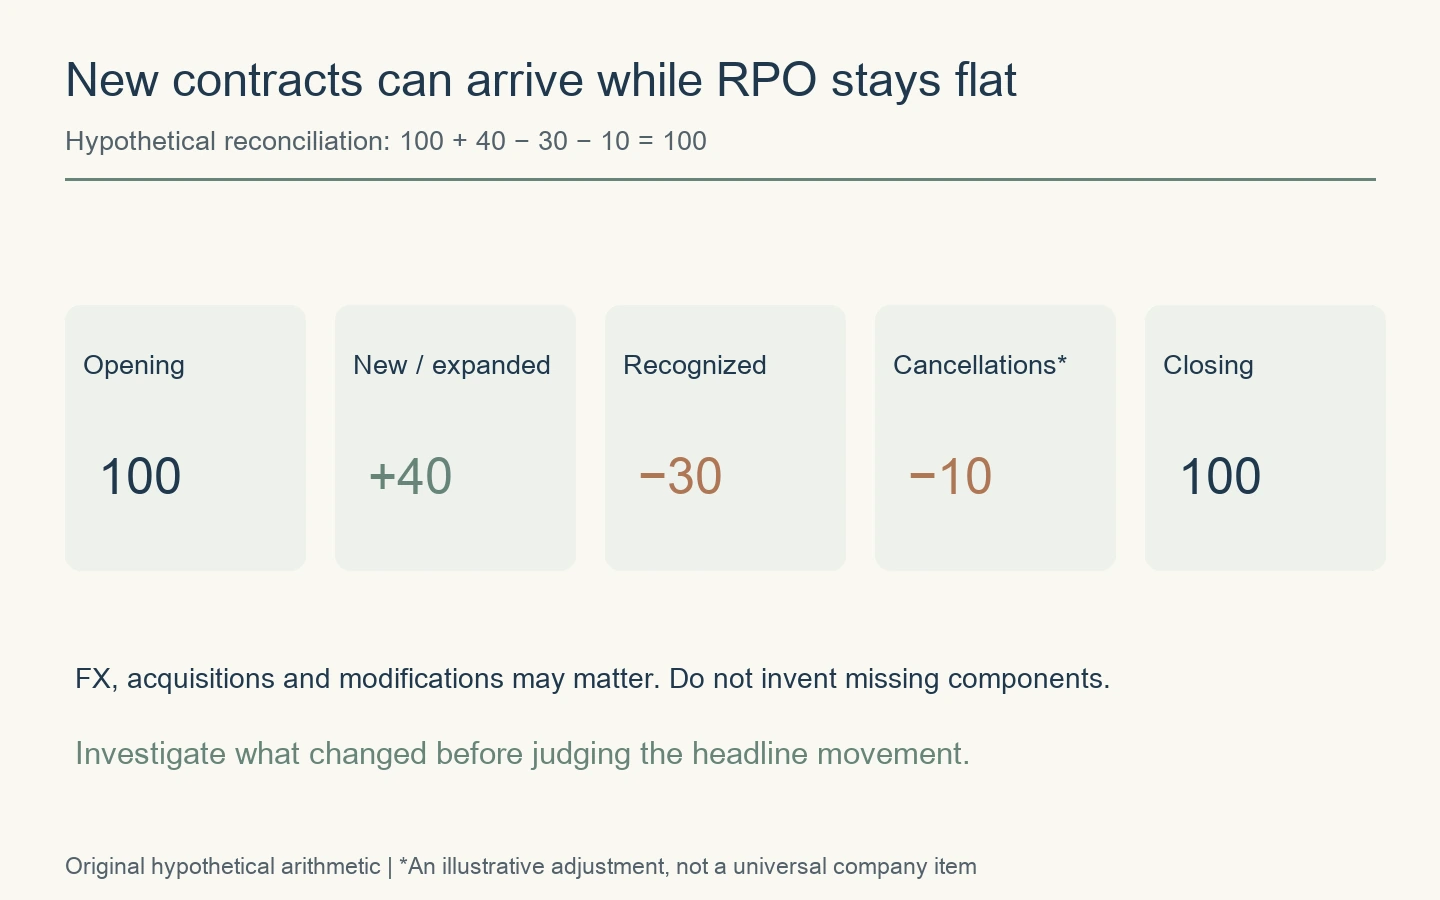
The balance did not grow, but new commitments were not zero. Conversely, extending contract lengths can lift total RPO without producing an equally large increase in next year’s revenue. Inspect the movement rather than assigning a verdict to the headline.
My working sheet would have separate columns for total RPO, expected twelve-month recognition, actual revenue, collections and funding. Unknown contract terms stay unknown. A neat spreadsheet is not worth false precision about customer cancellation rights or undisclosed bookings.
Advertisement
Seven checks for AI backlog and semiconductor investors
← Swipe to view the full table →
| Check | Evidence to read | Why it matters |
|---|---|---|
| Definition | RPO and backlog notes | Contracted amounts versus broader opportunity |
| Timing | Service starts and recognition bands | When delivery and revenue may occur |
| Counterparty | Customer concentration and conditions | Dependence on a few large plans |
| Execution | Power, facilities and equipment readiness | Constraints between contract and operation |
| Funding | Prepayments, debt, equity and leases | Who pays before collections arrive |
| Economics | Pricing, utilization and operating costs | Whether delivery leaves attractive margins |
| Valuation | Expectations and position size | A good contract need not be a good entry price |
Do not add a cloud customer’s contract value to GPU and memory supplier revenue and call the sum a new market. Those are different stages of the same economic chain. A multiyear service price also cannot be divided directly into today’s accelerator count without architecture, operating costs and timing assumptions.
The useful question for your holdings is specific: what must your company supply, when, under which terms, and at what return? If strong operating news still produces a weak share price, our post-earnings checklist addresses the gap between business performance and expectations.
Frequently asked questions about RPO
Is every RPO dollar non-cancellable?
A total does not reveal every contract’s legal provisions. Examine cancellation rights, modifications, variable consideration and estimation policies in the issuer’s notes. Do not turn the label into an unconditional cash guarantee.
Is falling RPO always a warning?
Delivery and revenue recognition also reduce it. The causes of the movement matter more than its direction alone.
Does a large backlog make equity dilution irrelevant?
No. If facilities must be financed before collections, funding terms still matter. Examine borrowing costs, share issuance and the economics after service begins.
Primary sources, calculations and updates
The company examples use Microsoft’s FY26 annual report and metric definitions, Oracle’s FY27 Q1 release and its dated FY26 funding explanation. The three diagrams and tables are original. They illustrate timing and reconciliation rather than reproduce source charts or estimate undisclosed bookings.
Future updates should refresh recognition schedules, scope and funding—not just replace the headline total. Undisclosed contract provisions remain unverified until reliable documentation becomes available.
Comments