
A long investment horizon does not guarantee that the fund you buy will exist for that whole period. An ETF can stop trading and liquidate, and an ordinary mutual fund can also close. Understanding the notice matters more than assuming that a familiar ticker will remain available forever.
This English adaptation of Y-bow’s fund-redemption article uses U.S. sources to explain the process, with an original diagram of an actual announced timetable. Local law, tax treatment and broker procedures differ. The example illustrates an announcement; it is not a recommendation to buy, sell or replace any particular investment.
Distinguish a liquidation from a normal sale or a merger
The SEC’s fund-liquidation bulletin describes a fund winding down, selling assets and generally paying shareholders cash. A merger instead transfers assets into another fund and normally gives investors shares in the acquiring fund. Notice requirements vary; a shareholder vote is not always required.
Neither event is the same as a routine redemption requested by one investor. And receiving cash at liquidation does not mean receiving your original purchase price. The relevant question is your share of the remaining assets, alongside costs and any distributions.
One announcement, several different dates
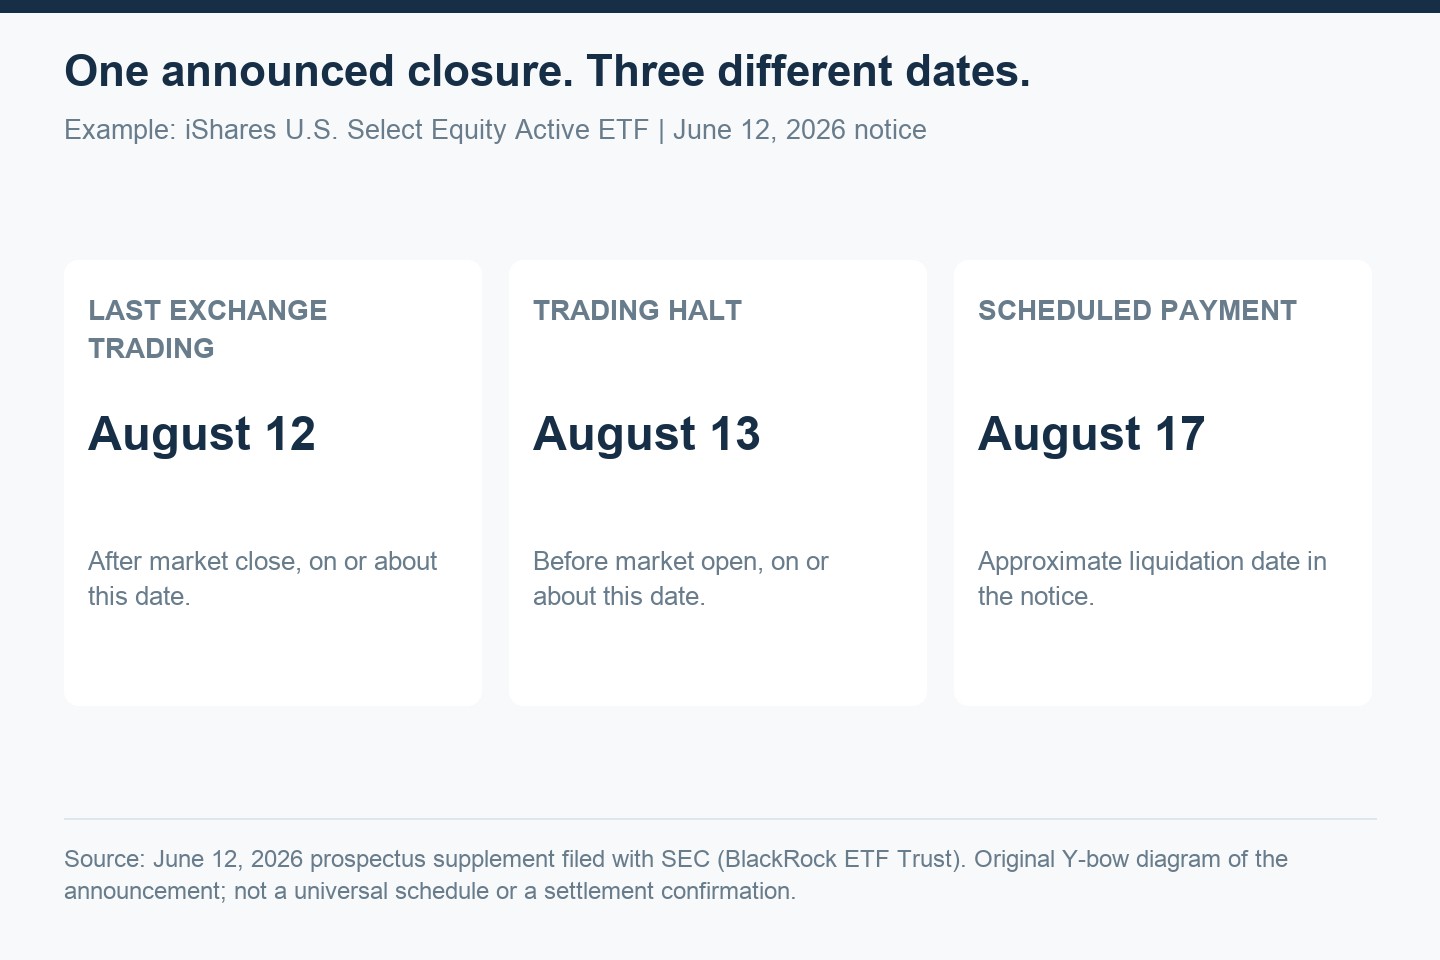
A June 12, 2026 prospectus supplement for the iShares U.S. Select Equity Active ETF announced a liquidation approved on June 11. It said exchange trading would end after the close on or about August 12, trading would be halted before the August 13 opening, and proceeds were scheduled on or about August 17.
The supplement also warned that preparation could change the fund’s investment approach. It described cash redemption using the relevant NAV and potential U.S. tax consequences. That country-specific statement is not a tax rule for every reader.
The diagram highlights a cash-flow question
August 13 to August 17 is four calendar days in this announced example. It is not four guaranteed trading days, and it does not establish when a particular broker would credit money to your account. A date on a fund notice and a date on your household cash-flow plan are different pieces of information.
Our interpretation is that a useful response separates the existing holding from the replacement decision. First establish what is happening to the fund and when. Then evaluate whether a replacement still serves the same purpose. Buying something with a similar name is not enough: index, leverage, currency exposure and fees may differ.
Read the notice rather than a generic closure checklist
According to the SEC bulletin, purchase cutoffs, redemption suspensions, trading stops and payment dates can differ. Less-liquid holdings can make the process slower. For an ETF, selling before trading stops and remaining for liquidation are different routes; the resulting price need not match an earlier quoted NAV or market price.
To organize the information, write down the exact fund name and share class, the notice date, the exchange’s last trading session and the expected payment date. Keep broker messages together with the issuer’s documents. If a scheduled contribution is still active, check what the broker says will happen to it rather than assuming it will automatically switch into another fund.
A closure does not answer the whole investment question
A fund is an implementation of an investment strategy. Its closure can interrupt that implementation without proving that the underlying market has become worthless. Equally, a replacement fund’s existence does not make it suitable. Separate the reason for holding an exposure from the mechanics of a particular wrapper.
Our ETF-versus-mutual-fund guide explains NAV and market-price differences. For why discontinued funds matter when reading past performance, see survivorship bias. Sources checked October 12, 2026. Educational explanation; original analysis and diagram by Y-bow. Japanese counterpart.
Comments