
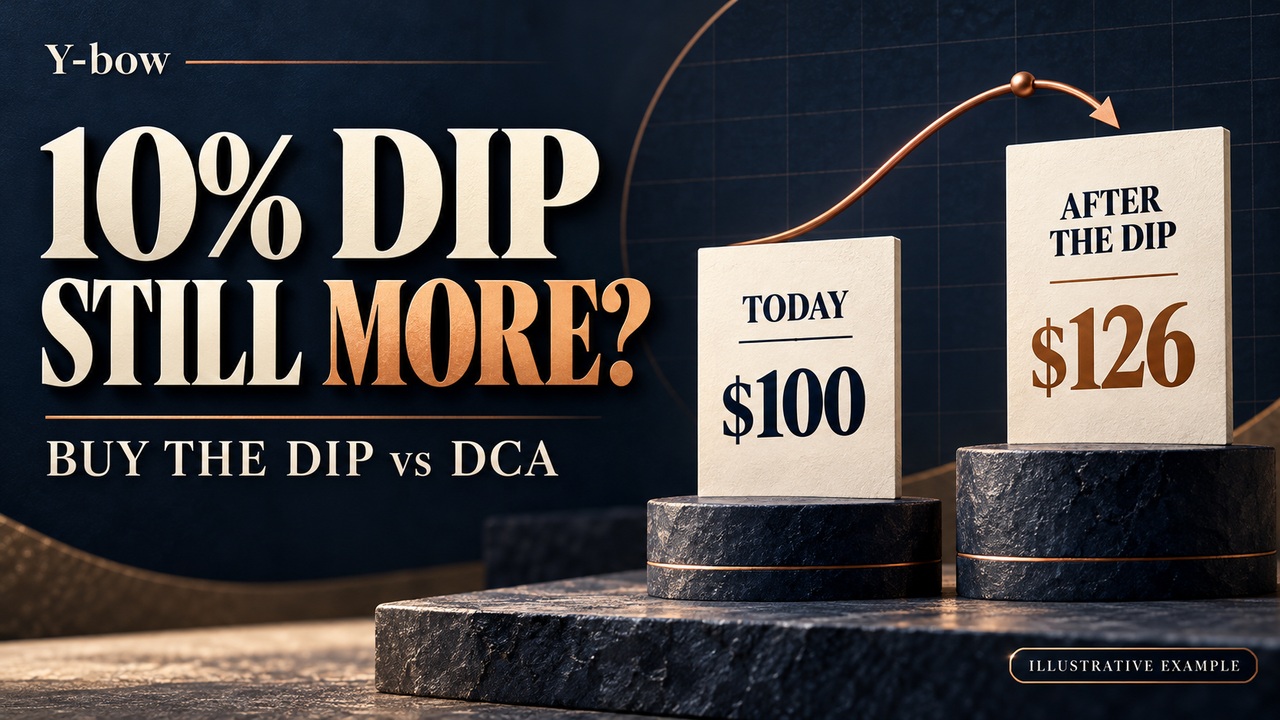
A 10% market dip can still leave you paying more than the price available today. If a fund rises from $100 to $140 and then falls 10%, its price is $126: 26% above where you first considered buying. The missing detail in “buy the dip” is the reference price.
To compare buying the dip vs dollar-cost averaging (DCA), define both rules before looking at the outcome. This guide uses the same $6,000 starting budget, three observation dates and three fictional price paths. Waiting helps in one path and lags in the others. None is a forecast or an estimate of which strategy is likely to win.
This is episode three of Investing, Visualized. Start with averaging down and dollar losses, then DCA vs lump sum for the earlier comparisons.
Watch Buy the Dip vs DCA on YouTube.
Buy the dip vs DCA: what is the difference?
A dip strategy waits for a specified price condition before investing. DCA invests equal cash amounts at fixed intervals regardless of price movements, as described by Investor.gov. A DCA purchase may happen during a dip, but the dip is not what triggers the scheduled purchase.
A price-triggered rule needs more detail than “wait for a correction.” Is the threshold measured from today’s price, a recent high, an all-time high, or your own purchase cost? How frequently do you observe it? How much do you buy, and what happens if the trigger never arrives?
A 10% dip from a later high is not 10% below today
At a $100 starting price, a fixed target 10% below today is $90. If a later observed high is $140, a price 10% below that high is $126. A moving reference high changes the purchase level.
$100 × 1.40 × 0.90 = $126.
The 40% rise and 10% fall multiply. Subtracting 10 percentage points from 40% gives the wrong answer because the fall applies to $140, not $100. The final gain from the starting price is 26%.
More generally, after a rise of r and a dip of d, both written as decimals, the price relative to the start is (1 + r) × (1 − d). A 10% dip returns a high of $111.111… to $100. A preceding rise larger than 11.111…% therefore leaves the dipped price above the start. This formula describes a relationship; it does not predict a market high or a correction.
The fair comparison: $6,000 and three explicit rules
All $6,000 is available on January 1 after money needed for other purposes has been set aside. The three methods use the same fictional, unleveraged fund in US dollars:
- Buy now: invest $6,000 on January 1.
- Fixed DCA: invest $2,000 on January 1, February 1 and March 1.
- Wait for the dip: start the running reference high at January’s price. On the first observation at least 10% below the highest observed price since January 1, invest the full $6,000 once. If no trigger occurs by March 1, retain the cash for this comparison.
Model assumptions: observe prices only on the three stated dates; assume execution at those prices; value all accounts immediately after the March 1 purchases. Fractional units are allowed. Cash earns no interest. We exclude fees, taxes, distributions and currency changes. There are no unobserved intraperiod prices in this constructed model. More frequent observations, market gaps and real execution can change the trigger and purchase price.
This is a comparison of existing cash. If money arrives with each paycheck, future contributions are not available to invest on January 1. The unused-cash comparison must respect when each dollar actually becomes available.
Path A: the dip arrives after a rally
The observed unit prices are $100, $140 and $126. Buying now acquires 60 units at $100. At the final $126 price, those units are worth $7,560.
The dip rule does nothing in February because the price has risen. February sets the observed high at $140. The March price is exactly 10% below it, so the rule buys then. Spending $6,000 at $126 buys 1,000/21 units, or approximately 47.6190 units. Their value immediately after purchase is still $6,000.
The dip buyer has no investment loss at that instant under our assumptions, but ends $1,560 behind buying in January. This is an opportunity cost, not an extra cash charge or an out-of-pocket loss.
What does DCA buy in the same path?
| Date | Price | Cash invested | Units bought | Value at final $126 price |
|---|---|---|---|---|
| January 1 | $100 | $2,000 | 20 | $2,520 |
| February 1 | $140 | $2,000 | 100/7 ≈ 14.2857 | $1,800 |
| March 1 | $126 | $2,000 | 1,000/63 ≈ 15.8730 | $2,000 |
| Total | — | $6,000 | 3,160/63 ≈ 50.1587 | $6,320 |
The fixed schedule finishes $320 above its starting budget, between buying now and waiting. It does not need to identify either the peak or the dip. Its outcome still depends on the price path.
Include the cash while it waits
Immediately after February’s scheduled purchase, buying now holds 60 units worth $8,400. DCA holds approximately 34.2857 units worth $4,800 plus $2,000 of cash, for $6,800 in total. The dip strategy holds $6,000 in cash. Comparing only invested assets would discard part of the DCA and waiting budgets.
Path B: the decline comes first
Now prices are $100, $90 and $90. The dip rule buys in February at $90, below January’s price. Its approximately 66.6667 units are worth $6,000 at the final $90 price. Buying now owns 60 units worth $5,400. DCA buys 20 units, then 200/9 units on each later date, ending with $5,800.
Waiting finishes ahead in this path. It avoided the initial decline while holding cash. That useful counterexample prevents the misleading conclusion that waiting can never help.
A dip trigger is not a price floor
Change the last price from $90 to $81. A dip buyer who invested $6,000 at $90 now has $5,400, a $600 loss. The trigger identified a decline from the reference high; it did not identify the bottom. A company can deteriorate further, and a fund can continue falling.
Path C: the dip never arrives before the deadline
In the third main path, prices are $100, $110 and $120. No observation is 10% below the running high. The waiting method ends with $6,000 in cash, not with missing or zero wealth.
Buying now ends at $7,200. DCA owns 20 + 200/11 + 50/3 units and ends at 72,400/11 dollars, approximately $6,581.82. Waiting did not create a cash loss, but it missed the rise in this particular path.
Compare total wealth at the same endpoint
| Observed prices: Jan → Feb → Mar | Buy now | Fixed DCA | Wait for the 10% dip | Dip-rule action |
|---|---|---|---|---|
| A: $100 → $140 → $126 | $7,560 | $6,320 | $6,000 | Buy March 1 |
| B: $100 → $90 → $90 | $5,400 | $5,800 | $6,000 | Buy February 1 |
| C: $100 → $110 → $120 | $7,200 | $6,581.82 | $6,000 | Remain in cash |
The table explains mechanisms rather than estimating which rule wins most often. One favorable example out of three does not imply a one-third success rate. The comparison would change with cash interest, distributions, trading costs, different observation dates or a different investment.
What historical research adds—and what it cannot tell you
PWL Capital’s “Buy the Dip” research tests waiting rules across several stock-market indexes and reports no compelling evidence favoring waiting for declines under its study design. Its historical rules and horizons differ from our short illustration. We do not reproduce its backtest or use it to assign odds to the next dip.
Schwab’s market-timing comparison includes a hypothetical investor who buys at each year’s lowest point. That is a hindsight benchmark, not an implementable advance signal. Comparing a live rule with an investor who already knows the year’s low confuses a decision process with knowledge available only later.
Broader evidence can inform a plan. It cannot tell you today’s future low, ensure a recovery, or make an unsuitable allocation appropriate.
Write a complete buy-the-dip rule
| Rule component | Question to answer before testing |
|---|---|
| Reference | Today’s price, a rolling high, an all-time high, or purchase cost? |
| Threshold | How large a decline, and measured using which price series? |
| Observation and execution | Which dates or frequency? What if the price gaps through the threshold? |
| Budget | What amount is invested once the trigger appears? |
| Deadline | How long will the money wait, and what is the no-trigger action? |
| Real-world adjustments | Cash interest, costs, taxes, distributions, currency and available funds? |
Keep emergency reserves and near-term spending separate from the investment budget. Choosing to hold cash for an upcoming bill is an allocation and liquidity decision, not automatically failed market timing. A low price also does not solve concentration, leverage or an impaired investment case. Our market-fall review guide helps separate those questions.
Frequently asked questions
Is buying the dip better than dollar-cost averaging?
There is no answer without specified rules, cash availability, costs and a price path. In the examples above, the dip rule helps after an early fall, lags after an early rally, and remains in cash when no trigger arrives. Selected examples do not establish future odds.
Why can a 10% correction still mean a higher purchase price?
The correction is measured from its reference high. A rise from $100 to $140 followed by a 10% correction ends at $126. That is below the high, but above the original $100 price.
Is a fixed buy price the same as a drawdown trigger?
No. A $90 target set from today’s $100 price stays at $90. A rule 10% below a moving high can trigger at $126 after the high reaches $140. Real order types and execution also require separate consideration.
Can a dip continue after I buy?
Yes. Buying at $90 after a decline does not prevent a further fall to $81 or lower. In the simplified $6,000 purchase, $81 leaves $5,400 before costs. A threshold is a purchase condition, not a capital guarantee.
Sources and calculation method
- Investor.gov: Dollar Cost Averaging — scheduled-purchase terminology.
- PWL Capital: “Buy the Dip” — historical research context.
- Charles Schwab: Does Market Timing Work? — comparison of timing approaches and a hindsight benchmark.
Prepared October 18, 2026. Prices and dates are constructed examples, not actual fund performance. Calculations use exact fractions, including an independent running-high trigger calculation. No return or success probability is predicted. AI assists production; the explanation, assumptions, calculations and sources are reviewed. Educational information only, not personalized investment advice. No guaranteed returns.

Comments