
SOXS suddenly appears to be trading at ten times its previous price. If you have watched a losing position for months, that can look like a recovery. Then you notice that the share count in your account has fallen.
Start with both sides of the multiplication: shares times price. A reverse split consolidates shares into larger units. The corporate action itself does not restore money previously lost.
Checked October 24, 2026. This guide concerns US-listed Direxion Daily Semiconductor Bear 3X ETF, SOXS. All numerical examples are hypothetical and are not a reconstruction of an actual trade or a jurisdiction-specific tax calculation.
What a SOXS reverse split changes
In a one-for-ten reverse split, ten old shares become one new share. In the simple no-price-movement case, the unit price becomes ten times larger. A 100-share position at $2 becomes ten shares at $20.
Direxion’s June 10, 2026 announcement specifies a one-for-ten reverse split for SOXS and explains that the split itself does not change total investment value, apart from fractional-share redemption. The market can still move: the first actual post-split trade is not guaranteed to equal exactly ten times the prior close.
Split-ratio wording can also be confusing across data services. Read the sentence explaining how many old shares become how many new shares. Do not rely on an isolated ratio without understanding its direction.
A worked example: share count, cost basis and an existing loss
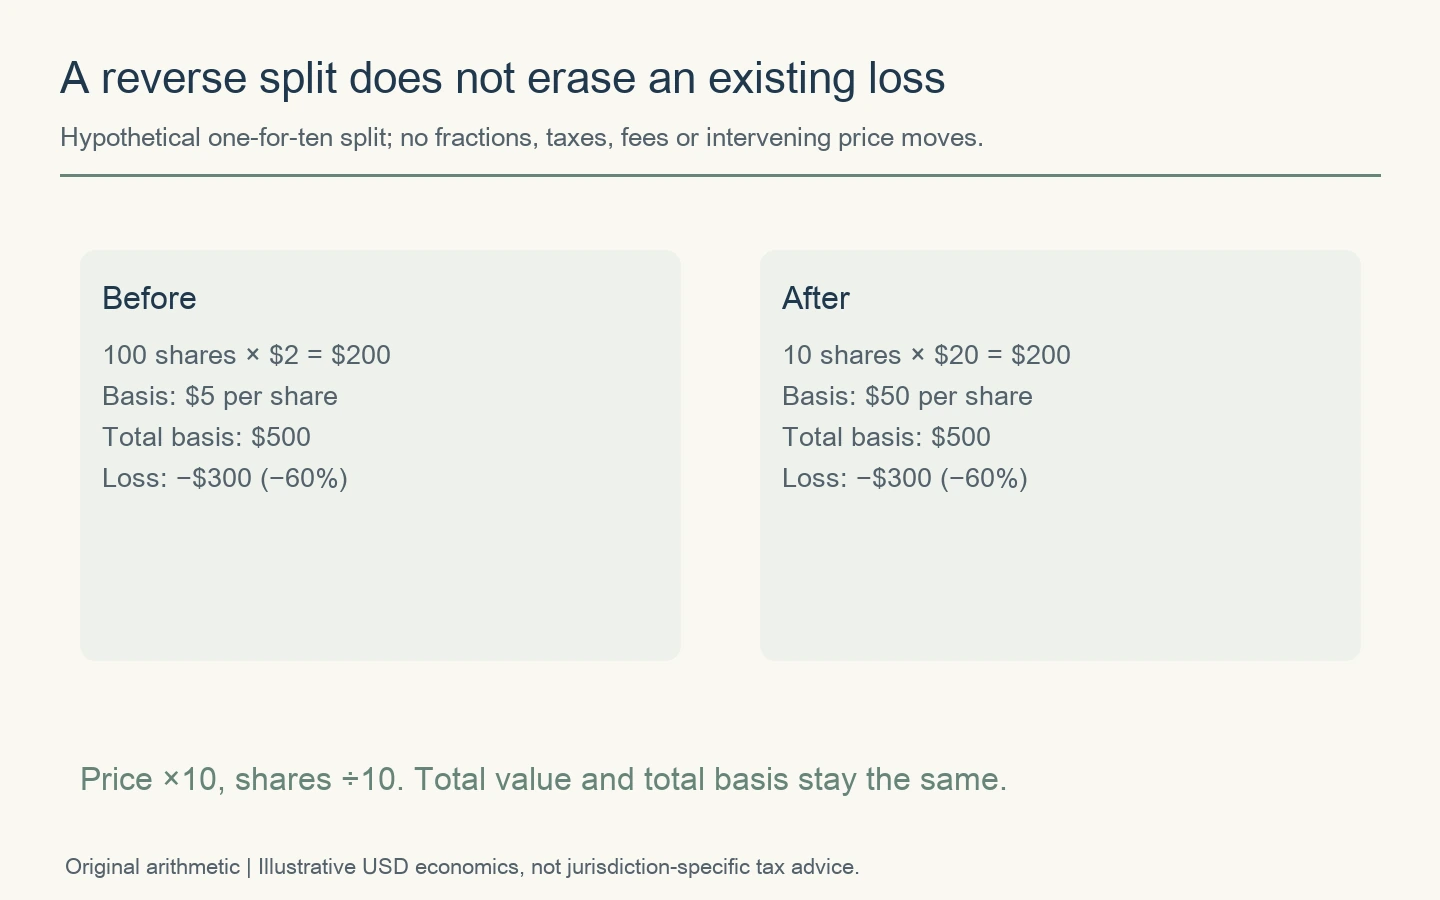
Assume you bought 100 shares at $5, for a total basis of $500. The market price subsequently falls to $2. Your position is worth $200, with an unrealized loss of $300, or 60% of the original basis.
After a hypothetical one-for-ten reverse split, assuming no fractions or intervening price movement, you have ten shares priced at $20. Adjusted cost per share is $50. Total basis remains $500 and position value remains $200, so the loss remains $300.
| Item | Before | After |
|---|---|---|
| Shares | 100 | 10 |
| Market price per share | $2 | $20 |
| Adjusted cost per share | $5 | $50 |
| Total basis | $500 | $500 |
| Position value | $200 | $200 |
| Unrealized loss | $300 (60%) | $300 (60%) |
Why comparing the new $20 quote with the old $5 purchase price fails
Those prices use different share units. Compare the post-split quote with the adjusted $50 basis, not the old $5 basis. Otherwise a losing position can look like a profitable one purely because the denominator changed.
To recover from $200 to $500 in this example requires a 150% increase. A move from $2 to $5 before the split and a move from $20 to $50 afterward have the same percentage hurdle. Consolidating the shares does not reduce the return required to recover the loss.
Advertisement
Announcement date, effective date and adjusted trading date
The June announcement provides a practical reading example. SOXS’s reverse split was to take effect after the US market close on July 14, 2026, with split-adjusted trading beginning July 15. June 10 was the announcement date, not the date the share count changed.
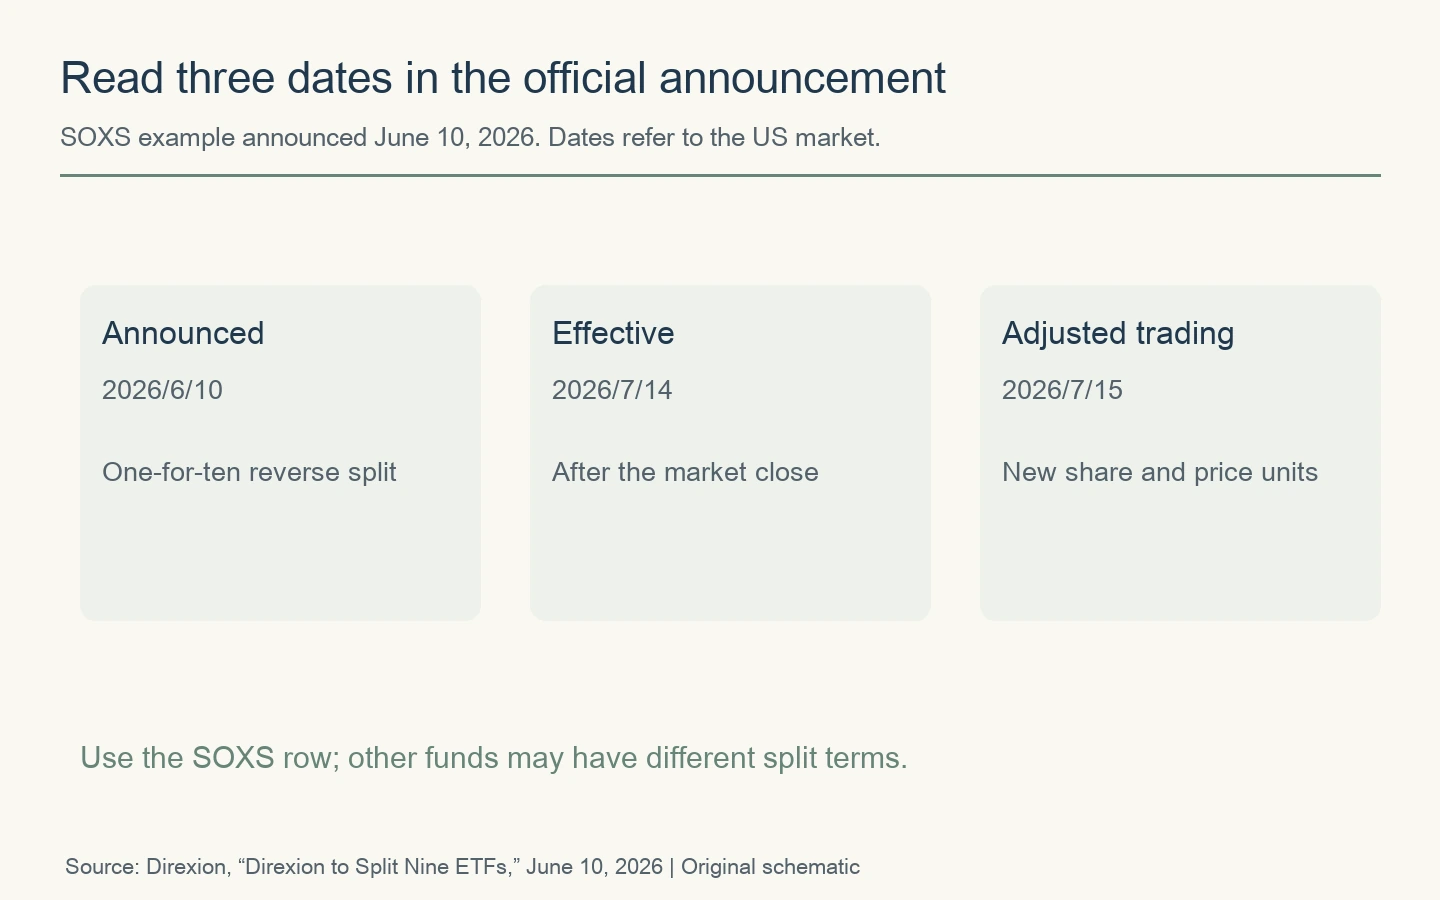
When a notice covers several ETFs, find the ticker, confirm forward versus reverse split, then read the relevant effective date. A forward split elsewhere in the same announcement can have the opposite effect on share count.
A separate February 4, 2026 notice also appears among the fund page’s operational updates. This article is not a verified complete history of every SOXS split. Use each new issuer notice rather than assuming the prior ratio or fractional-share terms will repeat.
Raw prices, split-adjusted charts and position value
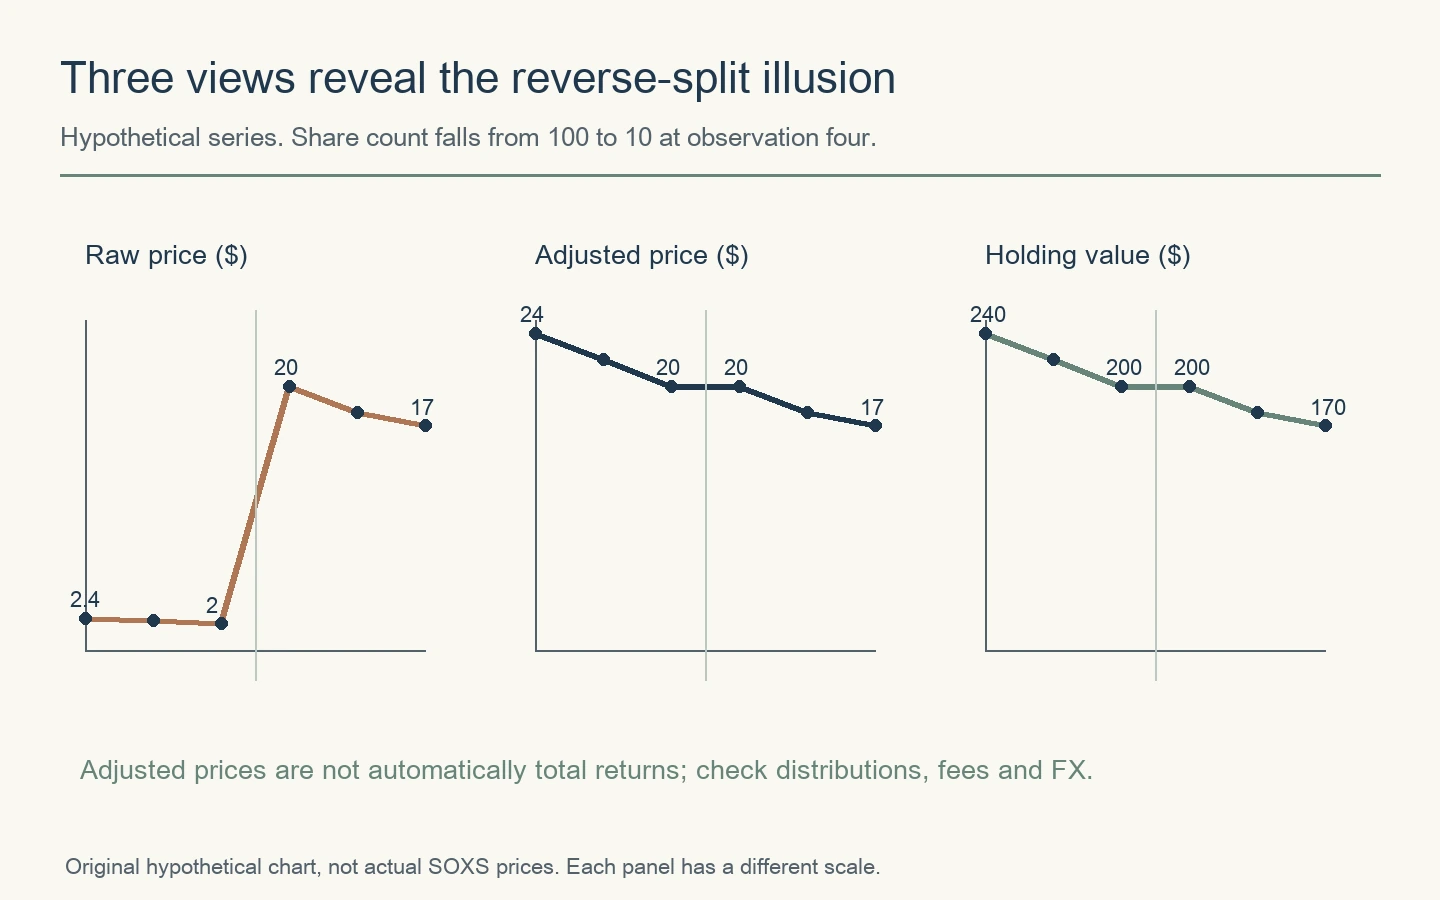
An unadjusted price series can jump at a reverse split. Calculating a return directly across that jump treats a change in share units as a gain. A split-adjusted series restates historical prices onto a consistent share basis.
Take an invented sequence of $2.40, $2.20, $2, $20, $18 and $17. Assume 100 shares before observation four and ten shares afterward. Position value is $240, $220, $200, $200, $180 and $170. There is no gain at the split even though the raw quote jumps.
Adjusted price is not automatically total return
A split-only adjustment and a distribution-reinvested total return are different measures. Data services may use “adjusted close” differently. Read whether the field includes distributions, not merely the word “adjusted.”
Your account adds another layer: purchase dates, additional trades, withdrawals, conversion costs, fees and taxes. A chart’s return from an arbitrary start date is not necessarily your personal return. Even a comparison with an old high needs consistent split units.
Fractional shares, cash in lieu and broker checks
Some holdings do not divide evenly. A hypothetical 105 old shares divided by ten produces 10.5 new shares. What happens to the fraction depends on the corporate-action terms and your broker’s implementation.
The June Direxion notice describes cash redemption of fractional shares at split-adjusted NAV. That does not, by itself, establish when your account will receive cash, which currency conversion applies, or your local tax result. A broker offering fractional-share trading does not guarantee identical treatment for a corporate action.
| Item | Check | If unclear |
|---|---|---|
| Share count and value | Whole shares, fraction and total position value | Review cash and corporate-action records |
| Cost basis | Consistent new share units | Do not rely on a temporary unadjusted display |
| Open orders | Cancellation, continuation or repricing rules | Read the broker’s current notice |
| Tax treatment | Cash in lieu and your jurisdiction | Use applicable official guidance or advice |
The worked example is denominated in dollars to explain the economic change in units. It does not settle tax-lot allocation, foreign-currency basis or taxation in every country. Those details need the rules applicable to your account and residence.
Does a SOXS reverse split signal a bottom or delisting?
The corporate action alone does not tell you the direction of the next market move. The SEC’s Investor.gov glossary explains that trading-price fluctuations after a reverse split can still produce losses. Any specific listing or termination event requires its own official notice.
SOXS seeks negative three times the NYSE Semiconductor Index’s daily return. That objective is separate from the arithmetic of a reverse split. It is not a promise of negative three times the index’s cumulative return over an arbitrary holding period.
If your concern is why a bearish ETF lost value over time, read our inverse-ETF daily-reset guide. A reverse split changes share units; it does not fix a mismatch between the product’s daily objective and your holding plan.
Once the account display is understood, return to the actual investment question: what exposure do you intend to hold, for what purpose, and under what conditions will you reassess it? A larger dollar quote does not answer those questions.
Sources, calculations and updates
Primary sources are Direxion’s June 10 notice, February 4 notice, product page and the SEC’s reverse-split explanation. The three diagrams are original. Calculations use shares times price, total basis divided by adjusted shares, and gain or loss divided by total basis.
New notices require a fresh check of ratio, dates and fractional-share terms. Hypothetical prices must not be relabeled as actual SOXS data. This is an educational explanation, not individualized trading or tax advice.
Comments