
A benchmark can recover to its starting level while an ideal daily 3x ETF remains down. The daily objective and the return over your holding period are different calculations. For SOXL and TQQQ investors, this can matter just as much as getting the AI or technology story right.
This guide focuses on the recovery trap, using original hypothetical paths. For the broader product overview, see SOXL explained: semiconductor exposure, daily leverage and drawdown risk. Product objectives checked October 18, 2026. No historical fund performance or forecast is used below.
Watch SOXL and TQQQ: The Daily 3x Recovery Trap on YouTube
SOXL and TQQQ target a daily return
SOXL seeks 300% of the NYSE Semiconductor Index’s daily performance before fees and expenses. TQQQ seeks 3× the Nasdaq-100 Index’s daily performance before fees and expenses. The benchmarks differ; the shared feature is daily leverage. Neither target is guaranteed. Direxion SOXL objective; ProShares TQQQ objective.
These products do not promise three times an index’s cumulative return over an arbitrary holding period. The SEC describes why results can diverge materially beyond one day. SEC investor bulletin.
The index-recovery trap: 100 → 120 → 100
Assumptions: a fictional benchmark and an ideal model that achieves exactly 3× each close-to-close daily return. Both start at 100. No fees, financing, taxes, distributions, cash flows, rebalancing or tracking differences are included. The deliberately large daily movements make the arithmetic visible; they are not typical-volatility estimates or probabilities.
| Step | Benchmark | Ideal daily 3x model |
|---|---|---|
| Start | 100 | 100 |
| Day 1: index +20% | 120 | 160 |
| Day 2: index −16⅔% | 100 | 80 |
| Two-day return | 0% | −20% |
The first day adds 20 to the benchmark and 60 to the model. Returning from 120 to 100 takes a decline of 20 ÷ 120 = 1/6, or 16⅔%. Three times that return is −50%. Half of the model’s new 160 balance is 80, so its final value is 80.
The model meets its daily target on both days. Its two-day loss comes from multiplying daily growth factors: (1 + 3 × 0.20) × (1 − 3 × 1/6) = 1.60 × 0.50 = 0.80. Multiplying the benchmark’s final 0% return by three would miss the mechanism.
Use the exact fraction in the calculation. Displaying −16.67% is convenient but introduces a small rounding difference. The model’s second-day dollar loss is 80, not 50, because the base is 160.
Repeated round trips compound the difference
| Completed two-day round trips | Benchmark level | Ideal daily 3x level |
|---|---|---|
| 0 | 100 | 100 |
| 1 | 100 | 80 |
| 2 | 100 | 64 |
| 3 | 100 | 51.20 |
Each pair multiplies the model’s value by 0.80. After three pairs, 100 × 0.80³ = 51.20, a 48.8% loss. The benchmark returns to 100 after each pair. This is a six-day fictional stress illustration, not an expected loss for SOXL or TQQQ.
The size of a real outcome depends on the actual daily-return pattern, costs and implementation. Do not turn a deliberately exaggerated teaching example into a predicted decline.
Same ending index level, different fund return
| Measure | Path A | Path B |
|---|---|---|
| Index daily returns | +10%, +10% | 0%, +21% |
| Index ending level | 121 | 121 |
| Ideal daily 3x ending level | 169 | 163 |
| Model holding-period return | +69% | +63% |
Path A uses 1.10 × 1.10 = 1.21 for the index and 1.30 × 1.30 = 1.69 for the model. Path B uses 1.00 × 1.21 = 1.21 for the index and 1.00 × 1.63 = 1.63 for the model. The same benchmark endpoint does not identify the model’s result.
Compounding can help: “always decays” is too broad
In Path A, the daily 3x model gains 69%, exceeding three times the index’s 21% holding return, or 63%. The word “decay” commonly describes the harmful effect of back-and-forth returns, but it is not a fixed annual deduction and does not mean every multi-day position loses. Fidelity illustrates how the daily path can help or hurt. Fidelity’s leveraged ETF explanation.
A favorable mathematical example is also not a suitability recommendation. Real costs and adverse moves still matter.
Does reversing the same daily returns change the result?
Not in this simplified constant-leverage model without cash flows. Reversing our initial pair gives 0.50 × 1.60 = 0.80, the same product. “Path dependence” means the index’s endpoint alone is insufficient; it does not mean that merely rearranging identical daily returns changes the final multiplication.
Adding cash, withdrawing or rebalancing on specific dates introduces a separate timing effect on an investor’s personal return. Identify those decisions explicitly before comparing strategies.
Recovery percentages use a smaller denominator
| Model value after loss | Gain needed to return to 100 |
|---|---|
| 80 | 25% |
| 64 | 56.25% |
| 51.20 | 95.3125% |
The formula is 100 ÷ remaining value − 1. A 20% loss requires 25% to recover. The 48.8% loss in the repeated illustration requires 95.3125%, or about 95.3%. These are arithmetic thresholds, not estimates of a future recovery’s likelihood or timing.
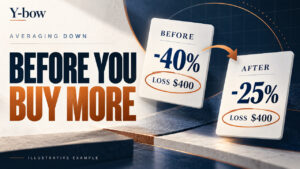
Averaging down changes average cost and exposure; it does not erase a prior loss. A DCA schedule does not remove daily resetting either. Evaluate the complete strategy, including each contribution and the alternative use of cash.
Translate fund risk into portfolio dollars
Suppose a portfolio starts at $10,000: $1,000 in the ideal daily 3x model and $9,000 in assets that remain unchanged. No cash flow or rebalance occurs during the two-day illustration.
| Quantity | Illustrative value |
|---|---|
| Capital allocation to model | $1,000 / $10,000 = 10% |
| Approximate starting targeted daily benchmark exposure | $3,000 / $10,000 = 30% |
| Loss from the initial two-day path | $1,000 × 20% = $200 |
| Portfolio return if everything else stays unchanged | −$200 / $10,000 = −2% |
The daily exposure comparison is an approximation of the target, not an exact multi-day portfolio beta. In a real technology shock, other holdings can fall simultaneously. Several ticker symbols can share the same economic driver.
A cash purchase of a leveraged ETF also differs from a personal margin loan. Borrowing to buy it adds another layer of leverage, interest and possible forced liquidation.
Compounding is different from tracking error and costs
The example loses money while hitting the daily target perfectly. FINRA makes the same conceptual distinction: multi-day divergence does not by itself show that a daily objective was missed. FINRA’s geared-product explanation.
Real funds additionally face expenses, financing and implementation effects. Investors face spreads, taxes and potentially currency conversion. Read the current prospectus and relevant footnotes. Do not assume one headline expense ratio represents every economic cost. For an actual performance comparison, state whether prices are NAV or market prices and how distributions are treated.
How this connects to the AI and memory-stock episodes
Episode four separates product demand, company profit and share valuation. Episode five tests whether cheaper DeepSeek AI changes customer and supplier economics. This episode adds the next bridge: the investment vehicle’s benchmark, leverage and holding-period behavior.
A correct semiconductor-business thesis cannot guarantee that a particular fund matches your horizon. SOXL and TQQQ are different portfolios, and neither directly delivers three times a favorite company’s earnings growth. The buy-the-dip waiting-cost episode also explains why the purchase rule must be specified instead of assumed.
Before using a daily leveraged ETF
- Identify the exact benchmark and current daily objective.
- Calculate an adverse path, including its portfolio dollar effect.
- Check overlap with other technology or semiconductor holdings.
- Read costs, implementation risks and any borrowing obligations.
- Define the holding period and what evidence triggers reassessment.
- Compare with an unleveraged alternative and the job the money must do.
Frequently asked questions
Can TQQQ or SOXL lose while its benchmark recovers?
Yes, a daily-reset mechanism can produce that outcome. The worked paths demonstrate the mechanism in an ideal model; they do not claim actual product performance over a particular period.
Do 3x ETFs always lose over time?
No. The favorable-trend example shows compounding can help. Actual outcomes also depend on daily returns, costs and implementation; suitability cannot be decided from that example alone.
Does DCA fix volatility decay?
Contributions change investor cash flows and exposure. They do not change the fund’s daily objective. A DCA strategy needs its own full calculation, including adverse paths.
Is the 20% loss a forecast?
No. It is the exact result of the stated fictional two-day path before costs. No probability or forecast is assigned.
Original calculations and analysis; AI-assisted diagrams, conceptual artwork and synthetic narration. Educational information, not personalized investment advice or a recommendation to buy or sell. No affiliate offer inserted. Sources and product objectives can change; consult current issuer documents.
After-market listening: 3 hours 10 minutes of original sleep music and relaxing BGM, with dim visuals and no talking. An optional companion for a quiet evening after your research.
Comments